Ten years after its first financing deal — a RM6,000 advance to a sole proprietor importing lab equipment — Malaysian fintech company Bay Group Holdings Sdn. Bhd., operating as CapBay, has facilitated more than RM6 billion in financing to over 2,700 small and medium-sized enterprises (SMEs) across 20 industries. The milestone, reported in an article published by The Edge Malaysia on 19 October 2026, is worth examining for what it reveals about how the company was built, what its leadership chose to do differently, and what the numbers say about the broader direction of SME financing in Malaysia.
- The Company: Built Around a Gap That Traditional Banks Left Open
- The Leader: Ang Xing Xian and the Decision to Start Small
- What They Did: Platform Design, Credit Methodology and Public Partnerships
- Results: 45,000 Financing Notes, RM6 Billion and One Client’s Account
- Impact: Sector Growth, Budget 2027 and What the Policy Signals Mean
- Looking at the Second Decade
The Company: Built Around a Gap That Traditional Banks Left Open
CapBay operates two platforms: a Supply Chain Finance platform and a Peer-to-Peer (P2P) Financing platform. Both are built on the same underlying premise — that many viable Malaysian businesses cannot access working capital quickly enough through conventional lending, not because they are weak, but because traditional credit assessment relies heavily on physical collateral such as property.
CapBay’s alternative is to assess businesses on live trading data: invoice validity, buyer payment records and actual transaction history rather than fixed assets. The company says this approach reduces approval times from months to days. For businesses in sectors where payrolls and supplier payments cannot wait for a customer’s invoice to clear, that speed is the practical difference between taking on a contract and turning it down.
The company has also positioned itself as a channel for public funding programmes. It serves as an appointed financial intermediary for SME Corp. Malaysia under the Ministry of Entrepreneur Development and Cooperatives (KUSKOP), and supports national schemes including BERKAT and RMK13 (Program-Program Pembiayaan Rancangan Malaysia Ke-13). It co-invests alongside public funds through the Malaysia Co-Investment Fund (MyCIF) and the NIMP Strategic Co-Investment Fund (CoSIF), both administered by the Securities Commission Malaysia (SC). It also collaborates with TERAJU for Bumiputera entrepreneurs and with the Malaysia Digital Economy Corporation (MDEC) under the MD Technology Financing Programme. These arrangements connect CapBay’s platform directly to priorities set out under the 13th Malaysia Plan, including the expansion of Malaysia’s digital economy.
The Leader: Ang Xing Xian and the Decision to Start Small
Ang Xing Xian is Co-Founder and Group CEO of CapBay. He co-founded the company alongside Edwin Tan and Darrel Ang. The sourced article does not detail the professional backgrounds of the three co-founders prior to establishing CapBay, so those details are not stated in the supplied sources.
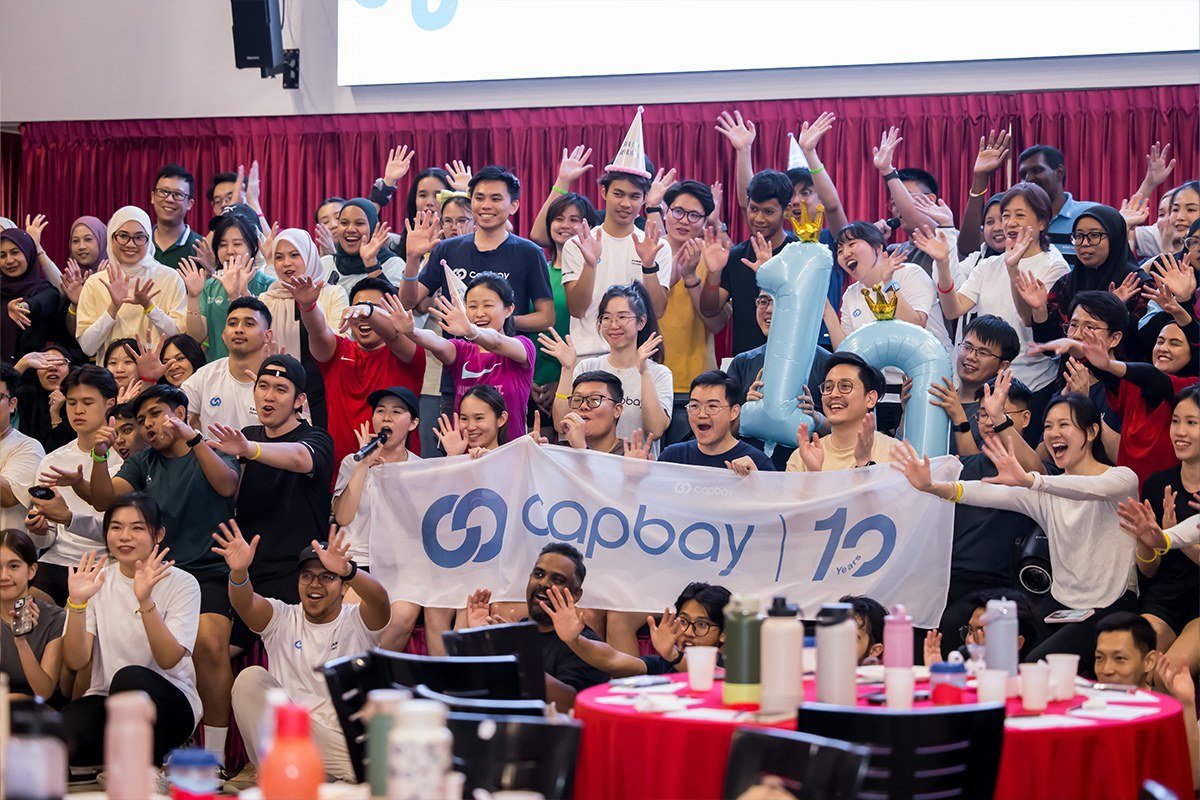
What the sourced material does record is Ang’s framing of the company’s first decade. Speaking at CapBay’s 10th anniversary, he described the RM6,000 opening transaction in explicit terms: a sole proprietor trying to bring lab equipment into Malaysia for a university. The deliberate choice to recall that specific transaction — small, unglamorous, operationally straightforward — appears to reflect a consistent position on what the business is trying to do.
“Ten years and 45,000 financing notes later, we’ve crossed RM6 billion. That number is not one we celebrate for its own sake. It is thousands of payrolls met, contracts delivered and businesses still trading,” Ang said, as quoted by The Edge Malaysia.
On the policy environment, Ang added: “Budget 2027’s support for P2P platforms confirms that regulated digital financing is now part of how Malaysia funds its SMEs. Our job in the next decade is to get that capital to every viable business that needs it.”
What They Did: Platform Design, Credit Methodology and Public Partnerships
The decisions that shaped CapBay’s first decade fall into two broad categories: how the platform assesses credit, and which institutional relationships it built to extend reach.
On credit methodology, CapBay moved away from collateral-based assessment toward a data-driven model that reads an applicant’s commercial activity — invoices issued, payment behaviour of their buyers, and trading patterns — to determine creditworthiness. The company describes this as allowing it to serve businesses that have genuine commercial traction but lack the fixed assets that banks traditionally require as security.
On institutional relationships, CapBay built connections across both the public and private sides of Malaysia’s SME support structure. The public-fund co-investment frameworks through MyCIF and CoSIF allow the platform to channel government-backed capital alongside private investor funds. The SME Corp. Malaysia intermediary role connects CapBay to national financing schemes. The TERAJU collaboration addresses Bumiputera entrepreneurship specifically, and the MDEC partnership ties the platform to the digital economy agenda.
The sourced article notes that CapBay is also developing AI-driven credit assessment capabilities, described as a priority for the company’s second decade. The specific features, timeline or performance benchmarks of that system are not detailed in the supplied sources.
Results: 45,000 Financing Notes, RM6 Billion and One Client’s Account
The figures CapBay disclosed at its 10th anniversary, as reported by The Edge Malaysia (19 October 2026), are as follows:
| Metric | Figure | As stated in supplied sources |
|---|---|---|
| Total financing facilitated | Over RM6 billion | Cumulative, 10 years to anniversary date |
| SMEs served | More than 2,700 | Across 20 industries |
| Total financing notes issued | 45,000 | Cumulative from inception |
| First financing deal | RM6,000 | Sole proprietor, lab equipment import |
The sourced article also includes a client account from Manforce Group Berhad, a workforce management firm. Andrew Chin, Finance Director of Manforce Group, described the core problem that CapBay addressed for his business: in workforce management, operational costs — specifically payroll — must be paid well before clients settle their invoices. That gap puts sustained pressure on cash flow as the business grows.
“Cash flow management is one of the most critical challenges for growing businesses, especially in workforce management where we must upfront significant operational costs on behalf of clients. Unlike traditional financing models, which focus heavily on physical collateral, CapBay took the time to understand our business model and offered flexible, considerate terms,” Chin said, as quoted by The Edge Malaysia.
Chin added that faster access to funds allowed Manforce Group to manage liquidity through the COVID-19 pandemic period and to continue expanding. The sourced article does not provide specific figures for Manforce Group’s financing volume or revenue growth, so those details are not stated in the supplied sources.
Impact: Sector Growth, Budget 2027 and What the Policy Signals Mean
CapBay’s decade of growth sits inside a broader shift in how Malaysia’s financial system approaches SME lending. The SC introduced its P2P regulatory framework in 2016. According to the SC Annual Report 2025, alternative financing avenues raised RM5.7 billion for MSMEs and mid-tier companies in 2025, a year-on-year increase of 39.0%. Within that total, P2P financing specifically raised RM2.8 billion in 2025, up from RM2.5 billion in 2024.
Those figures establish P2P financing as a channel of meaningful scale within the Malaysian financing system, not a peripheral experiment. CapBay’s RM6 billion cumulative total should be read against that context: the platform has been operating across the full period since the SC framework was established, and its volume represents a substantial portion of the market’s development.
Budget 2027, tabled on 9 October 2026, added two specific measures that affect the sector directly:
- The Government set aside RM270 million to draw private capital into SMEs, mid-tier companies and social enterprises through P2P financing and equity crowdfunding platforms.
- Stamp duty on financing agreements executed through P2P platforms was fixed at RM10 from 1 January 2027 to 31 December 2030.
The fixed stamp duty rate is a structural cost reduction for businesses using P2P platforms over a defined four-year window. The RM270 million allocation is intended to leverage additional private investment alongside the public commitment. Together, these measures indicate that the government views regulated digital financing platforms as an established and expandable part of Malaysia’s SME funding infrastructure, not simply a supplement to bank lending.
For CapBay, that policy direction aligns with the institutional position it has already built through its public-fund co-investment roles and its SME Corp. Malaysia intermediary appointment. As platforms registered with the SC, CapBay and its peers are now explicitly within the scope of national budget allocations — a different standing from where alternative finance sat a decade ago.
Looking at the Second Decade
CapBay enters its second decade with a stated agenda of deepening its public-private partnerships and advancing its AI-driven credit assessment. The practical question those ambitions raise is reach: whether the platform can extend its data-driven model to sectors and business sizes it has not yet served at scale, and whether the Budget 2027 framework will generate measurable increases in capital deployment to viable SMEs that currently cannot access working capital quickly enough.
The company’s starting point is a cumulative RM6 billion across 45,000 financing notes — built from a first deal worth RM6,000. The policy environment, as of Budget 2027 and the SC’s 2025 data, is more explicitly supportive of P2P platforms than at any previous point. What CapBay does with that combination — and whether the AI credit assessment it has signalled can extend its reach without compromising its stated focus on viable businesses — is the question that the next decade’s numbers will answer.